The pieces on a benefit's bidding table arrive months before the first bid. Committees assemble them through donor asks, business solicitations and board networks, a pipeline that runs long before doors open.
Tax rules shape the paperwork from the first letter. In one IRS example, a bidder paid $600 for a week's stay at a beach house and could claim nothing, because the price merely matched fair rental value, per Publication 526.
The same discipline matters once the bids are in, because the night's results feed cost-to-raise-a-dollar math. This piece follows an item from the wish list to the checkout table.
The wider world of benefits, from budgets to institutions, sits in the site's galas section. The table may look effortless, and none of it is.
Who Assembles the Item List
DonorPerfect's planning guide assigns the work to named owners, a roster that starts with "Donation item sourcing." Logistics and event marketing sit alongside it.
Board members carry weight in the ask. The same guide tells planners to ask whether board members' companies will sponsor, since cash and in-kind support "can help underwrite the silent auction."
Volunteers fill the gaps between staff leads, which keeps the workload off a small development team. Named owners also stop the list from doubling up on the same kind of prize.
How Silent Auction Items Get Solicited
Solicitation starts with a wish list matched to likely donors, then a letter that states the event, the date and what a gift supports. Businesses respond best to a specific ask, so committees name the piece they want rather than request anything at all.
A confirmed gift comes back with details the committee needs: a description and an estimated value, plus any limits on use. Those details travel to the catalog, the bid sheets and the acknowledgment letter.
Timing drives the calendar. Committees open the ask season well before the event, since businesses set their giving budgets early.
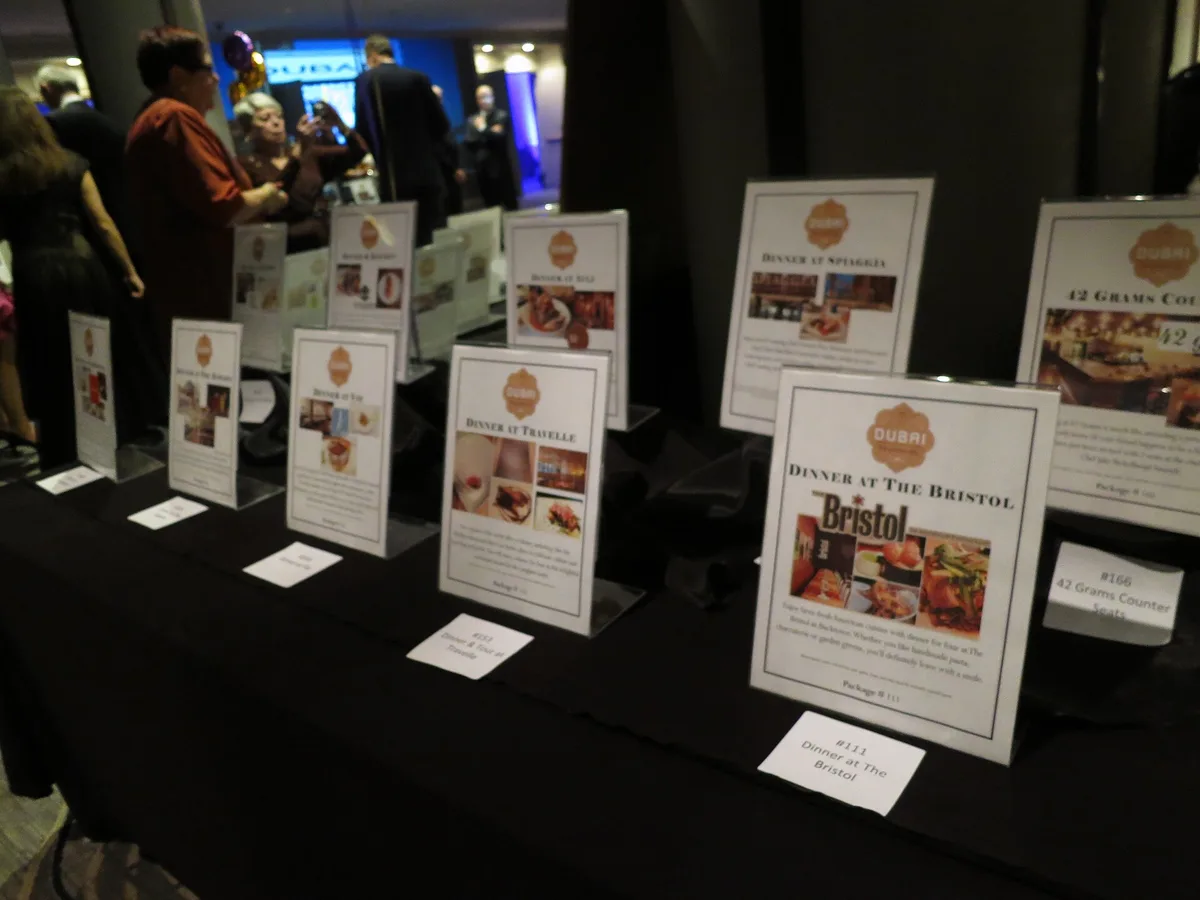
Bundling is a standard move, and DonorPerfect suggests pairing pieces to raise interest, such as a retreat package built around a set of smaller goods. We covered a connected angle in How Charity Galas Actually Raise Money for Their Causes.
What Donors Can Claim Under IRS Rules
A donor who gives an item claims its fair market value, not the price the bidder pays. Publication 561 puts the standard in one line: fair market value is the price agreed on between "a willing buyer and a willing seller."
The paperwork scales with size. Donors need a written acknowledgment from the charity, and larger gifts add Form 8283 and, in some cases, a qualified appraisal, per the publication. For related coverage, see Why Charity Galas Publish Audited Financials and Form 990.
The charity's letter describes the gift but states no value. IRS guidance reserves valuation for the donor and the agency, which keeps the auction desk out of the appraisal business.
Experience lots follow the same logic. A trip or a dinner carries the value of the benefit itself, and the rules for those packages live in the same publications.
How the Winner and the Charity Settle Up
The bidder who buys an item at a charity auction can deduct only the amount above its fair market value, per Publication 526. In the agency's example, a $600 payment equal to fair rental value produced no deduction at all.
Some gifts carry strings. A week at a vacation home, donated for auction, trips the partial interest rule, so neither the donor nor the winner may claim anything, per the same publication.
Checkout teams close the loop on the night itself, pairing each winning bid with its acknowledgment and its value notes. Records kept at this stage feed the next year's ask letters.
Conclusion: A Table Built One Ask at a Time
A silent auction reads as abundance, and each plate on the table has a paper trail: an owner, a letter, a value rule and an acknowledgment.
Committees that respect those steps end the night with clean files as well as receipts, and the charity keeps numbers it can defend.